Sunday, 20 March 2016
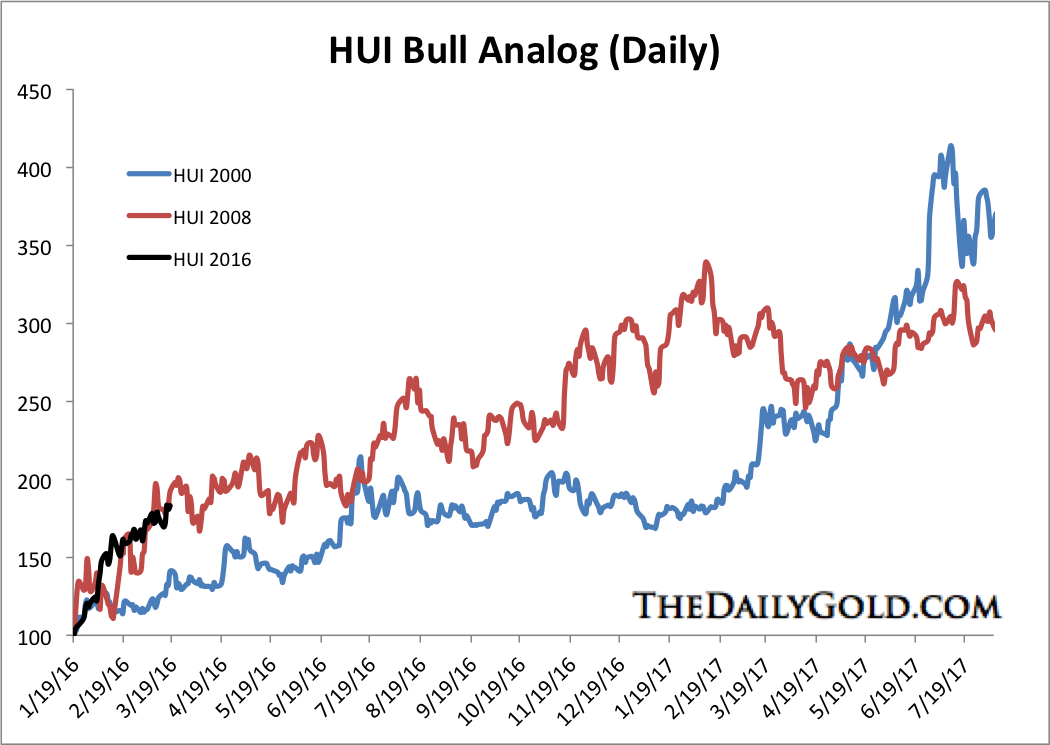
2016 Gold Stock Rally in Perspective
The fierce and persistent rally in Gold Stocks during 2016 has many awaiting a pullback. Jordan Roy-Byrne cautions against applying bear market analysis to a new bull.


Rick Rule Interview
Lessons of the last down cycle should last for 2-3 years and see gold miners earn increasing cashflow per share with a rise in gold prices, benefiting shareholders.
Identify senior and intermediate producers with growing revenues.
Real move in speculative stocks in 9 months, will be a spectacular market, understand depth and severity. Long long way to run with the correct stocks.
Precious metal streams very valuable to struggling base metals miners, streamers offer lowest cost of capital, increase quality and visibility of revenue stream, plus optionality on the streamed mine.
Loves 'optionality' companies, large deposits drilled off with nil NPV at the bottom of the cycle, must preserve the optionality, management must do almost nothing to dilute shareholders, merge and lower SG&A, number of projects then focus on the best. Spend money when the move has progressed and share prices have advanced. Easiest and most dramatic upside except for occasional discovery will be optionality plays. Preference with developement studied and permitted, but less likely. Power of private placements and warrants in micro-caps. Sellers and buyers are exhausted driving outsize moves with some bids.
Risk of appearance of being profitable during low commodity prices through high-grading.
Identify senior and intermediate producers with growing revenues.
Real move in speculative stocks in 9 months, will be a spectacular market, understand depth and severity. Long long way to run with the correct stocks.
Precious metal streams very valuable to struggling base metals miners, streamers offer lowest cost of capital, increase quality and visibility of revenue stream, plus optionality on the streamed mine.
Loves 'optionality' companies, large deposits drilled off with nil NPV at the bottom of the cycle, must preserve the optionality, management must do almost nothing to dilute shareholders, merge and lower SG&A, number of projects then focus on the best. Spend money when the move has progressed and share prices have advanced. Easiest and most dramatic upside except for occasional discovery will be optionality plays. Preference with developement studied and permitted, but less likely. Power of private placements and warrants in micro-caps. Sellers and buyers are exhausted driving outsize moves with some bids.
Risk of appearance of being profitable during low commodity prices through high-grading.
Brent Cook & Joe Mazumder at PDAC
Seeing fundamental drivers for this upturn in previous metals.
Companies with debt had higher levels of due diligence.
Streamed assets showed poorer quality.
Change in the industry and investors looking for returns, but how long will that last if gold heads back over $1,500
Companies with debt had higher levels of due diligence.
Streamed assets showed poorer quality.
Change in the industry and investors looking for returns, but how long will that last if gold heads back over $1,500
Wednesday, 16 March 2016
Druckenmiller 30% in Gold
At the end of 2015 Stanley Druckenmiller held 30% of the $1bn Duquesne family office fund in GLD. Druckenmiller accumulated around $1,200 during early/mid 2015.
Druckenmiller tipped his hand when he gave a speech during Q2 2015 where he said the following: “Our monetary policy is so much more reckless and so much more aggressively pushing the people in this room and everybody else out the risk curve that we're doubling down on the same policy that really put us there (in the 2008 financial crisis) and enabled those bad actors to do what they do. Now, no matter what you want to say about them, if we had had five or six percent interest rates, it (the housing bubble) would have never happened because they couldn't have gotten the money to do it.......This is crazy stuff we're doing. So, I would say you have to be on alert to that ending badly. Is it for sure going to end badly? Not necessarily. I don't quite know how we get out of this, but it's possible.”
Institutions - Gold & Negative Rates
Munich Re including gold investments
The world's largest reinsurer is far from alone in seeking alternative investment strategies to counter the near-zero or negative interest rates that reduce the income insurers require to pay out on policies. Munich Re has held gold in its coffers for some time and recently added a cash sum in in the two-digit million euros, Chief ExecutiveNikolaus von Bomhard told a news conference. "We are just trying it out, but you can see how serious the situation is," von Bomhard said. The ECB last week cut its main interest rate to zero and dropped the rate on its deposit facility to -0.4 percent from -0.3 percent, increasing the amount banks are charged to deposit funds with the central bank.
Wednesday, 3 February 2016
Life is What Happens
Life is what happens to you while you're busy making other plans.
Time to resume some blogging
Time to resume some blogging
Sunday, 7 June 2015
PWC - Mine 2015 - The Gloves are off
OT - UK Marginal Tax Rates
UK headline tax rates are not all they seem at certain earnings threshold levels, with various traps reviewed at the FT this weekend


John Kaiser & Others - Vancouver Canvest 2015
A roundup of all Coverage by Resource Investing News, including two interviews with John Kaiser discussing several of his regular picks.
Gold miners increasingly making bite-sized developments that carry less risk
Article at Business Insider
The cautious approach will likely persist even if conditions improve, with miners increasingly teaming up on big, complex projects to share costs, expertise and risk, senior mining executives and industry watchers said.......To be sure, not all mines can be built in phases and bigger projects will find fresh appeal when gold rebounds from the current $1,175 an ounce. "The market is short-term focused," said Jeannes at Goldcorp. "If the gold price were $1,800 an ounce and the equity markets were wide open . . . our investors would be questioning us if we weren't going for the full, large, build-out." But miners have learned from the past five years, said Joseph Foster, portfolio manager at Van Eck, Barrick's biggest shareholder. "I don't think we'll see the capital cost blowouts and the margin squeezes going forward that we have in the past," Foster said. "They've learned a very hard lesson and I don't think they'll forget it."
Saturday, 6 June 2015
Brent Cook at Vancouver Canvest 2015
Reporting HERE
Another who likes Dalradian and Kaminak.
Ross Beaty invested significantly in both.
Also Brent Cook Interview on Al Korelin Show - segment 6
Discusses, and owns
Another who likes Dalradian and Kaminak.
Ross Beaty invested significantly in both.
Also Brent Cook Interview on Al Korelin Show - segment 6
- "Getting a bit more positive on the sector"
- Lack of discoveries, looking blind, under cover, more drilling, more complex metallurgy at depth, more strip, therefore own the few economic deposits that work or those capable of finding them
- Accumulating over summer
- Industry wastes too much money on projects that never stand a chance.
Discusses, and owns
- Premier Gold, cash and 2 big projects in Nevada and JV with Centerra in Ontario.
- Focus ventures - high margin potential phosphate project in Peru
- B2 Gold following buyout of Papillon. Namibia and Mali high margin developments
- Companies with cash to last over 1.5 years, and high margin legitimate projects with good people..
Avoiding 100's of juniors with market caps under $15m with no project, no cash, can go to zero. So little money out there to finance high capex low margin deposits, leads to continual dilution.
Another Interview HERE
Another Interview HERE
Really, if you own 10 solid companies that are doing solid work and have the money to stay alive and have a deposit or discovery that looks like it’s going to work, that’s all you need. You don’t need 50 companies.Discusses and Owns
- Pilot Gold
- Mirasol (JV with Yamana)
- Mariana Resources "I was just there looking at it. It’s pretty darn interesting. It’s certainly a discovery. It’s got high-grade potential" (See Interview at PDAC)
- Likes / Owns - Fission Uranium, Denison Mines, Energy Fuels. "because they’ve got a lot of resources drilled out, permitted, ready to go. I would not spend a dime looking for uranium. There is so much uranium out there. It’s just waiting on higher prices."
Thursday, 4 June 2015
Sunday, 31 May 2015
Eric Coffin Interview - Vancouver Show & Metals Investor Forum
As reported at IKN the traditionally large scale Cambridge House Vancouver Show looks to be poorly attended this year as junior metals exploration falls further out of favour and the companies involved run shorter of cash.
A more select "forum" has been put together with some well known letter writers.
Highlighted companies include - Eric Coffin's Liongold, Goldquest - John Kaiser on Sabina - Brien Lundin on Balmoral & Fission 3 - Gwen Preston's Kaminak & Pilot Gold. - Nevsun and First Mining Finance also announced attendance.
Post Show Review of 12 presenting companies
Eric Coffin in discussion with Gwen Preston
A more select "forum" has been put together with some well known letter writers.
Highlighted companies include - Eric Coffin's Liongold, Goldquest - John Kaiser on Sabina - Brien Lundin on Balmoral & Fission 3 - Gwen Preston's Kaminak & Pilot Gold. - Nevsun and First Mining Finance also announced attendance.
Post Show Review of 12 presenting companies
Eric Coffin in discussion with Gwen Preston
The Real Value of Gold in the Ground - Mickey Fulp / Cipher Research
Mercenary Geologist Mickey Fulp continues to publish an interesting series of deeper studies with Cipher Research.
Previously looking at the real long term costs and profitability of gold mining and "adequacy ratios".
The recent publication looks at the more junior "gold in the ground" explorers and developers, identifying points of over and under-valuation.
A case study of Rainy River, (with it's perfect bull ending at the start of 2011), subsequently bought out by New Gold makes clear the cycles of value creation and destruction for investors buying at different points in the discovery and development process and in particular during the bull and bear phases when capital floods in and out of the relatively small gold mining market. Valuations are leveraged to peak and increasing gold prices rather than more conservative and eventually pessimistic assumptions.
Whilst Fulp dismisses Rainy River as never being on his radar due to over-valuation it is clear that in bull markets for gold miners go-to stories emerge which can move well over "fair value". Value is far easier to find in bear markets but cheap can get cheaper until the turn.
Fulp leaves with some checklists to consider
Previously looking at the real long term costs and profitability of gold mining and "adequacy ratios".
The recent publication looks at the more junior "gold in the ground" explorers and developers, identifying points of over and under-valuation.
A case study of Rainy River, (with it's perfect bull ending at the start of 2011), subsequently bought out by New Gold makes clear the cycles of value creation and destruction for investors buying at different points in the discovery and development process and in particular during the bull and bear phases when capital floods in and out of the relatively small gold mining market. Valuations are leveraged to peak and increasing gold prices rather than more conservative and eventually pessimistic assumptions.
Whilst Fulp dismisses Rainy River as never being on his radar due to over-valuation it is clear that in bull markets for gold miners go-to stories emerge which can move well over "fair value". Value is far easier to find in bear markets but cheap can get cheaper until the turn.
Fulp leaves with some checklists to consider
- Because the consulting engineering firms operate in a highly competitive business environment, they are hired with the expectation of tailoring technical reports to the client’s needs and desires.....For this reason, investors must scrutinize engineering reports carefully. It is often necessary to make adjustments to the assumptions and key variables to arrive at a more realistic project value at any point in time........As an aside, have you ever come across a negative feasibility study? Remember folks, for every failed mine, there was a positive feasibility study
- Too often we find the so-called “experts” that lay investors choose to rely upon are not experts at all. Instead they are brokers, investment bankers, or in-house promoters whose primary interest is in collecting commissions or fees for selling stock, deals, and private placements, or earning consulting fees from the company....Folks, please make sure that you understand the motivations of any expert, analyst, broker, promoter, writer, or talking head whose advice you choose to follow. Here are a few questions you can ask that will afford valuable insight into this matter:
- Does he own shares in the company and at what price?
- Is he participating in the deal or placement with his own personal funds?
- Will he collect a commission or fees for selling you the stock or deal?
- Does he get paid to promote the company via fees, stock, and/or options?
- Is he or his firm underwriting the deal for a fee, commission, and/or warrants?
- Will he give you a full disclosure statement regarding his financial relationship with the company and/or project?
John Kaiser Interview
Interview At Korelin
Kaiser believes the better juniors have bottomed while sentiment is 1/10.
Discussion of Eastmain Resources as a destination for investors bought out of Probe by Goldcorp. Believes adding value through increasing understanding of the structural controls, spent too long in the past drilling and exploring, PEA due for current deposit plus future exploration potential.
Kaiser "Tracker" report on Eastmain (much of Kaiser's work can be followed free after a short period)

Deposit comparables from Eastmain's presentation


Kaiser believes the better juniors have bottomed while sentiment is 1/10.
Discussion of Eastmain Resources as a destination for investors bought out of Probe by Goldcorp. Believes adding value through increasing understanding of the structural controls, spent too long in the past drilling and exploring, PEA due for current deposit plus future exploration potential.
Kaiser "Tracker" report on Eastmain (much of Kaiser's work can be followed free after a short period)
Deposit comparables from Eastmain's presentation


Sunday, 17 May 2015
Peter Brandt - Turns Bullish on Silver
Peter Brandt called the bear in 2011 and is now bullishly inclined
I am moving into a state of high alert in Silver. While I still am inclined to trade a breakout in either direction (given a measured-risk entry), my preference is now slanted toward the buy side. Silver could become rather exciting during the weeks ahead.
Eric Coffin Gold Stock Picks
A number of Coffin's recent write ups have seen significant moves. Interview at The Gold Report with picks.
Sunday, 10 May 2015
6 Juniors that have soared in 2015
Smallcap-Power
Canadian high grade / turnaround - Claude, Eastmain, Kirkland Lake
Nevada high grade - Klondex
Senegal backed by Franco Nevada - Teranga
Toll Processor - Dynacor
Canadian high grade / turnaround - Claude, Eastmain, Kirkland Lake
Nevada high grade - Klondex
Senegal backed by Franco Nevada - Teranga
Toll Processor - Dynacor
Saturday, 9 May 2015
Wednesday, 6 May 2015
Calling Bond Bear Markets
Quite a few big names pointing to a potential bottom in interest rates and peak in bonds.
Calafia Beach pundit commentary and analysis.


Gary Tanashian points out that the bond bull "continuum" is still very much in place

Calafia Beach pundit commentary and analysis.
What prompted me to make this call? It was the recent 47 bps bounce in 10-year German bund yields, off of an incredible low of 0.05% a few weeks ago.Whereas Armstrong suggests a final blow off top in bonds, as stock markets dip, and divergent strength in the US against European before the true rush from government debt & bonds floods into the US stock market.
Gary Tanashian points out that the bond bull "continuum" is still very much in place

UK Election - Austerity
Looking like a very tight result and another coalition to come.
Acting-Man discusses the reality of the UK economy.
Why would Armstrong imagine a Bond crisis?


Sunday, 3 May 2015
Martin Armstrong on the end of cash - negative interest rates - bond bubbles and Gold
Armstrong's recent focus on controls of cash holdings, negative interest rates and debt/bond bubbles coming into the September 2015 period. Some would see a role for gold, Armstrong suggests not yet.....more.....
Jordan Roy Byrne - Relative Strength in the Miners - Plus Stock Picks
Interview at Kitco
Stock Picks.

Stock Picks.
- Likes Bear Creek Mining, very cheap, believes silver market will turn, Corani world class asset.
- Kirkland Lake Gold - turnaround stock, reserves. Price near 2 year high, room to move higher. (JGMS - Eric Sprott recently on board here)
- Doesn't like prospect generators, unlike many others. Sees sense of the model, the promotion is that they are safer. Charts and performance are mostly poor. Gambling stocks on exploration drillholes.
- Real interest rates driving gold. Expects 2015 bottom.
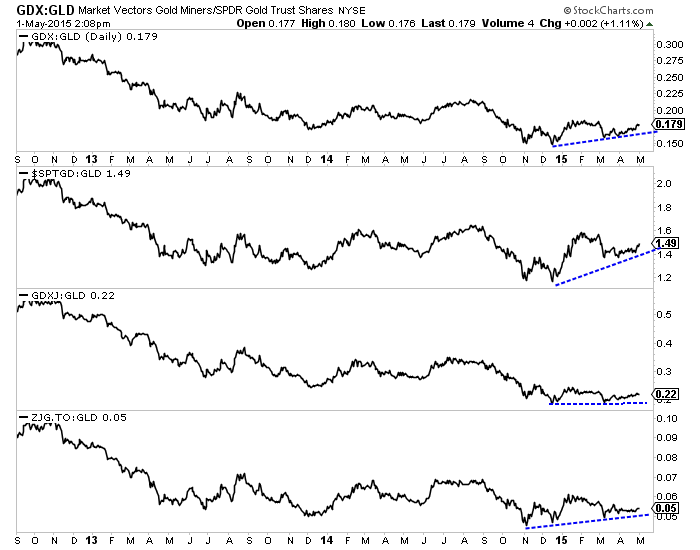
Recent article sees relative strength in the gold stocks even during gold's recent price decline as significant and evidence that gold miners may have bottomed relative to gold.
The reasons for the gold miners’ relative strength are unlikely to be temporary. Sure Oil has rebounded but its price remains well below the $100/barrel it averaged throughout 2011 to 2014. That is helping miners. In addition, local currency weakness has been a boon
Jim Rogers - Waiting for US Dollar Bubble Top to Buy More Gold
Interview with Jim Rogers. Still likes stocks in China, Russia, Japan.
Waiting for US$ bubble top to buy more gold, maybe....(on gold from start of interview)
Sees US rate hike, market dip, easing, blow off top.
Waiting for US$ bubble top to buy more gold, maybe....(on gold from start of interview)
Sees US rate hike, market dip, easing, blow off top.
Saturday, 2 May 2015
Why the Rush into Canadian Gold Mines May Continue - Sprott's Todoruk
The weak Canadian dollar is making Canada's relatively safe jurisdiction more appealing for acquisitions. The same argument might be put for Australian deposits yet the majors have made a number of divestments, is their need to strengthen balance sheets forcing sales?
Todoruk's short list of appealing Canadians includes
Todoruk's short list of appealing Canadians includes
a short list of well-followed companies would include Detour Gold for its Detour Lake mine, Pretivm Resources for its large, high-grade Valley of the Kings deposit, Rubicon Minerals for its very near-production Phoenix gold mine, Richmont Mines with its Island Gold mine, Lakeshore Gold with its producing gold mines in the Timmins mining camp, Kirkland Lake with its producing mine in eastern Canada, and Kaminak Gold which owns the Coffee gold deposit in the Yukon.
Friday, 1 May 2015
Tuesday, 28 April 2015
Sunday, 26 April 2015
Junior Gold M&A - Novacopper buy Sunward.
Some big names, Thomas Kaplan's Electrum, John Paulson, and Seth Klarman's Baupost have been significant holders of Sunward, trading below their high $20m cash (no debt).
Sunward hold a very large scale (global top 3%) low grade (0.53g au) Gold-copper deposit, Titiribi, in Colombia which has yet to see an economic study, but would presumably be a project requiring a much higher real gold price and then be highly leveraged to the 10m oz + gold (mostly inferred) & 800m lb copper.
NovaCopper have many of the same holders. The acquistion appears to look to apply Sunward's cash to advance NovaCopper's Alaskan copper deposits.

Sunward hold a very large scale (global top 3%) low grade (0.53g au) Gold-copper deposit, Titiribi, in Colombia which has yet to see an economic study, but would presumably be a project requiring a much higher real gold price and then be highly leveraged to the 10m oz + gold (mostly inferred) & 800m lb copper.
NovaCopper have many of the same holders. The acquistion appears to look to apply Sunward's cash to advance NovaCopper's Alaskan copper deposits.
Eric Coffin can still draw the crowds
The junior market can still come alive to a good promo by a respected letter writer. The 5 year chart puts the 40%+ increase in perspective. This one went out to Coffin's email list and also via CEOca which appears to be getting in with Brent Cook, Coffin, Roulston and Sprott.
Perhaps it helped that juniors with deposits have been seeing M&A bids.

Perhaps it helped that juniors with deposits have been seeing M&A bids.
Thursday, 23 April 2015
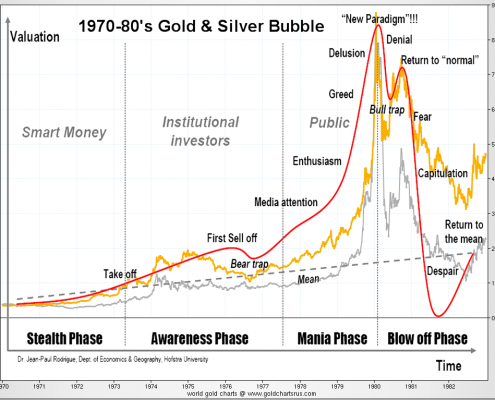
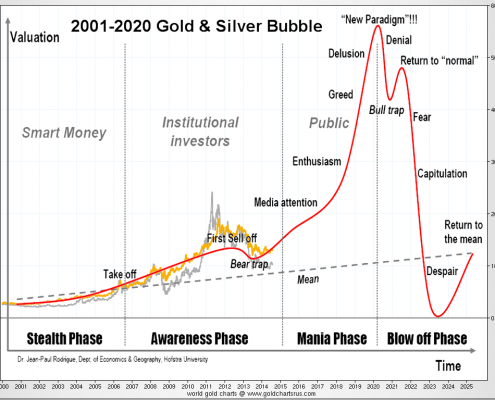
Gold Bubbles
Chris Vermeulen has cooled on gold for the past few years but is suggesting the bull resumes later this year. Clearly if both the charts below spanned the same period, the 2011 peak was it.
Taking Steve Saville's analysis of the "1970s" gold bull however he would show the real move in the miners starting in the 1960s even while the metal price was fixed.


Taking Steve Saville's analysis of the "1970s" gold bull however he would show the real move in the miners starting in the 1960s even while the metal price was fixed.
Wednesday, 22 April 2015
Drill Baby Drill
You thought 2ft concrete walls would protect your valuables?
Details of Easter Robbery of safety deposit boxes in Hatton Garden, London

Details of Easter Robbery of safety deposit boxes in Hatton Garden, London

Tuesday, 21 April 2015
Aussie Gold Mines for Sale - Newcrest's Telfer and Barrick's Cowal
More Aussie Gold assets look to be hitting the market with Newcrest named as both potential buyer and seller.
- Newcrest and Hecla amongst bidders for Barrick's Cowal, 1.5m oz P&P, 270k oz production @ $740-$775 AISC
- Bank of America Merrill Lynch seeking bids for Newcrest's Telfer mine, >500k oz gold production 2014
Monday, 20 April 2015
Gold Miner M&A - Evolution Mining bid for La Mancha Australia Assets
Evolution will grow to 530-600k oz pa -
La Mancha will own ~30% and provide $100m cash for more growth.
Presentation

La Mancha will own ~30% and provide $100m cash for more growth.
Presentation
Saturday, 18 April 2015
Sprott launch Junior Gold Mining ETF - SGDJ
Sprott have followed the launch if their Gold Miners ETF - SGDM with a Junior Gold Miners version - SGDJ.
There are a couple of conflicting messages
What are the SGDJ holdings? Are they different from GDXJ Holdings or BMO's ZJG Holdings?
Sprott have less royalty here, B2 and Centerra are much more significant and the x3 silver miners stand out, though I recall GDXJ started out with a high % of silver miners.
So how has Sprott's senior Gold Miner ETF - SGDM fared since launch against GDX Holdings?
Not so good.
Here they have a policy of high exposure to "stronger balance sheets" in particular Randgold and Franco Nevada, which did not suffer to the degree Barrick, Goldcorp and Newmont did and have not seen the same rebounds.

There are a couple of conflicting messages
Very junior discovery activity seems out of bounds (similarly even "GLDX explorers ETF holdings" are mainly developers of well explored and defined deposits, so really just taking the producing aspect out of GDXJ).
- "Why invest in junior miners? -"High-value discoveries and mine development can create enormous upside potential" ..........But......."The Index methodology tends to favor junior and intermediate producers versus early stage exploration companies whose historical success rate is low."
What are the SGDJ holdings? Are they different from GDXJ Holdings or BMO's ZJG Holdings?
Sprott have less royalty here, B2 and Centerra are much more significant and the x3 silver miners stand out, though I recall GDXJ started out with a high % of silver miners.
| COMPANY | TICKER | Weight % |
| B2Gold Corp | BTO CN | 7.71% |
| Centerra Gold Inc | CG CN | 6.46% |
| First Majestic Silver Corp | AG US | 6.08% |
| Hecla Mining Co | HL US | 5.63% |
| Pan American Silver Corp | PAAS US | 5.60% |
| Alamos Gold Inc | AGI CN | 5.23% |
| Harmony Gold Mng-Spon ADR | HMY US | 4.23% |
| IAMGOLD Corp | IAG US | 4.16% |
| Primero Mining Corp | PPP US | 3.72% |
| OceanaGold Corp | OGC CN | 3.47% |
| Sandstorm Gold Ltd | SAND US | 3.41% |
| Aurico Gold Inc | AUQ US | 3.17% |
| Detour Gold Corp | DGC CN | 3.00% |
| Rio Alto Mining Ltd | RIO CN | 2.74% |
| China Gold International Res | CGG CN | 2.69% |
| Nevsun Resources Ltd | NSU CN | 2.65% |
| Alacer Gold Corp | ASR CN | 2.59% |
| Kirkland Lake Gold Inc | KGI CN | 2.57% |
| Lake Shore Gold Corp | LSG CN | 2.47% |
| Novagold Resources Inc | NG US | 2.26% |
| Argonaut Gold Inc | AR CN | 2.22% |
| Semafo Inc | SMF CN | 2.05% |
| Fortuna Silver Mines Inc | FSM US | 1.87% |
| Silver Standard Resources | SSRI US | 1.67% |
| Endeavour Silver Corp | EXK US | 1.55% |
| Dundee Precious Metals Inc | DPM CN | 1.47% |
| Torex Gold Resources Inc | TXG CN | 1.46% |
| Gold Resource Corp | GORO US | 1.37% |
| Pretium Resources Inc | PVG US | 1.22% |
| Rubicon Minerals Corp | RBY US | 1.04% |
| Premier Gold Mines Ltd | PG CN | 0.97% |
| Mag Silver Corp | MAG CN | 0.78% |
| Seabridge Gold Inc | SA US | 0.71% |
| Guyana Goldfields Inc | GUY CN | 0.66% |
| Asanko Gold Inc | AKG CN | 0.59% |
| Continental Gold Ltd | CNL CN | 0.53% |
So how has Sprott's senior Gold Miner ETF - SGDM fared since launch against GDX Holdings?
Not so good.
Here they have a policy of high exposure to "stronger balance sheets" in particular Randgold and Franco Nevada, which did not suffer to the degree Barrick, Goldcorp and Newmont did and have not seen the same rebounds.
Canada's Discovery Performance - Richard Schodde - MinEx Consulting
Another interesting presentation from Richard Schodde at MinEx (many more presntations here including Pacific region)
Covering the volatility of exploration spending, the importance of juniors in discoveries and the rarity and importance to valuation of tier 1 and 2 discoveries.


Covering the volatility of exploration spending, the importance of juniors in discoveries and the rarity and importance to valuation of tier 1 and 2 discoveries.
$1Bn Quebec Mining Fund
Reported at Pierce Points and Bloomberg
While Finance Minister Carlos Leitao announced plans for the fund in June, Quebec’s legislature has yet to authorize its creation. Capital Mines Hydrocarbures should be able to support as many as 10 mining projects once it begins operating, Daoust said. “The raison d’etre of that fund is to make sure that at the end of the day, if the funding is complicated for the last 10 or 20 percent of a project, we will be there,” the minister said. “We can go to C$200 million, but normally we should not invest more than 10 or 15 percent of a project.”
Friday, 17 April 2015
Subscribe to:
Posts (Atom)